The Cost of Living Isn’t Going Away: What Does the Latest News Mean for Your Money?
If it feels like your money isn’t going quite as far as it used to, you’re certainly not alone.
Despite hopes that the cost-of-living crisis would begin to ease, the latest economic figures suggest that households and businesses could be facing another challenging period.
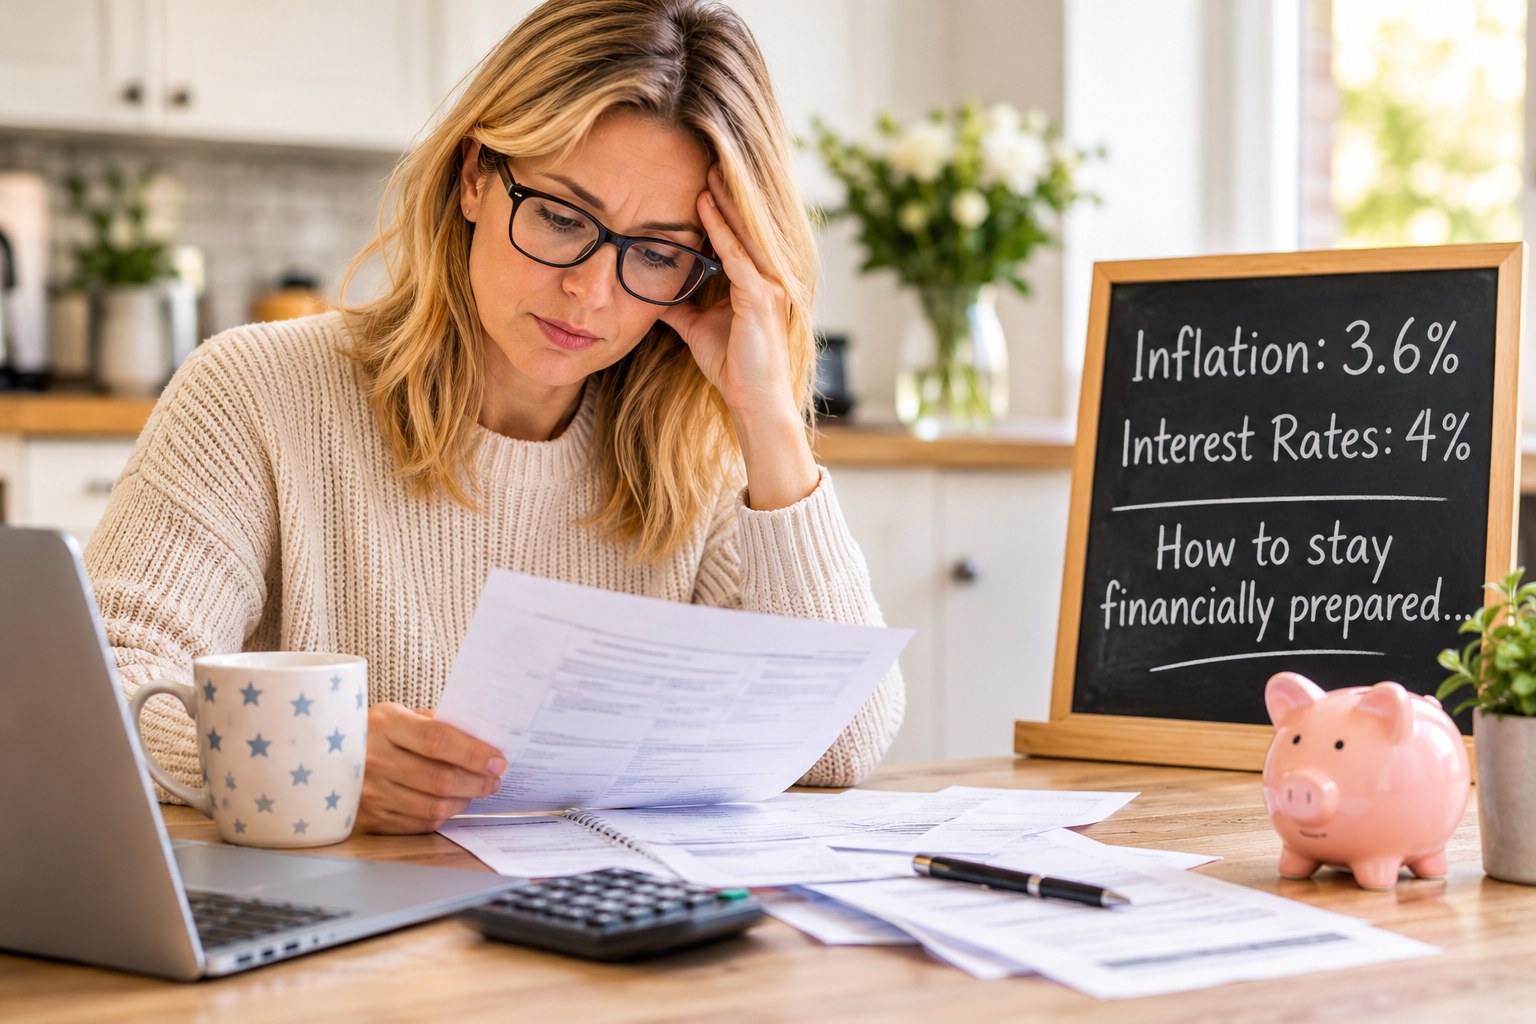
New figures released in November show that UK inflation has risen to 3.6%, up from 3.5% the previous month. Meanwhile, the Bank of England has increased interest rates to 4%, adding further pressure for those with mortgages, loans and other borrowing.
But what does all this actually mean for everyday life, and what can we do to stay financially prepared?
Why are prices still rising?
Inflation measures how quickly the prices of goods and services increase over time. Although inflation has come down considerably from the highs experienced in 2022, that doesn’t mean prices have returned to where they were.
In fact, it’s quite the opposite.
Food shopping, household bills, fuel, insurance and everyday essentials have all become more expensive over recent years. Even when inflation slows, prices generally continue to rise, just at a slower rate.
The latest figures show that transport costs have been a particular pressure, with prices in this category rising by 7.5% over the year to October.
For many families, this means having to think twice about purchases that would previously have been considered perfectly affordable.
What does this mean for homeowners?
Interest rates are another important factor.
The Bank of England’s recent decision to increase its base rate to 4% could have consequences for mortgage holders, particularly those approaching the end of a fixed-rate deal or currently on a variable-rate mortgage.
Higher borrowing costs can also make it harder for first-time buyers to get onto the property ladder, while homeowners may find that moving house or remortgaging becomes more expensive.
For anyone with a mortgage renewal approaching, planning ahead and reviewing the household budget is particularly important.
Are businesses feeling the pressure too?
It’s not just households feeling the squeeze.
Businesses are also dealing with increased operating costs, from energy and premises expenses to wages, supplies and insurance.
For small businesses in particular, these increases can make it increasingly difficult to maintain profit margins without passing some of the additional costs on to customers.
However, increasing prices isn’t always straightforward. Customers are feeling the pressure too, and businesses need to strike a careful balance between remaining competitive and protecting their profitability.
This makes keeping a close eye on cash flow more important than ever.
Five ways to take control of your finances
Although we can’t control inflation or interest rates, there are steps we can take to put ourselves in a stronger financial position.
1. Review your regular spending
Take a look at subscriptions, insurance policies and monthly direct debits. Small savings across several expenses can make a noticeable difference over a year.
2. Shop around
Don’t automatically renew insurance, utilities or other services without checking whether a better deal is available.
3. Review your borrowing
If you have loans, credit cards or a mortgage renewal coming up, understand what higher interest rates could mean for your monthly commitments.
4. Build an emergency buffer
Where possible, try to put a little money aside each month. Having some savings available can make unexpected expenses much easier to manage.
5. Keep your finances organised
Whether you’re managing a household budget or running a business, understanding exactly what’s coming in and going out is one of the best ways to stay in control.
Looking ahead
There is no doubt that the economic outlook remains uncertain, and the latest figures are a reminder that financial pressures haven’t disappeared.
However, being proactive, reviewing your finances regularly and planning ahead can make a real difference.
For businesses, understanding the numbers behind the operation is just as important as bringing in new customers. For households, having a clear picture of monthly spending can help avoid unnecessary financial stress.
Our advice? Don’t wait until money becomes tight before reviewing your finances. A little forward planning today can make a big difference tomorrow.
If you’re a business owner and would like a clearer picture of your finances, we’re always happy to help.